
Utah Homeownership Authority
TresThe Magic Mortgage LenderPowered by JMJ Financial Group
Condos & Townhomes · Knowledge Center · UHA-0045

Condo vs. Townhome: What Utah Buyers Should Know

Ownership form, project approval, HOA dues, insurance, and the true monthly cost of an attached Utah home.

By Tres MillerSeptember 7, 202610 min read
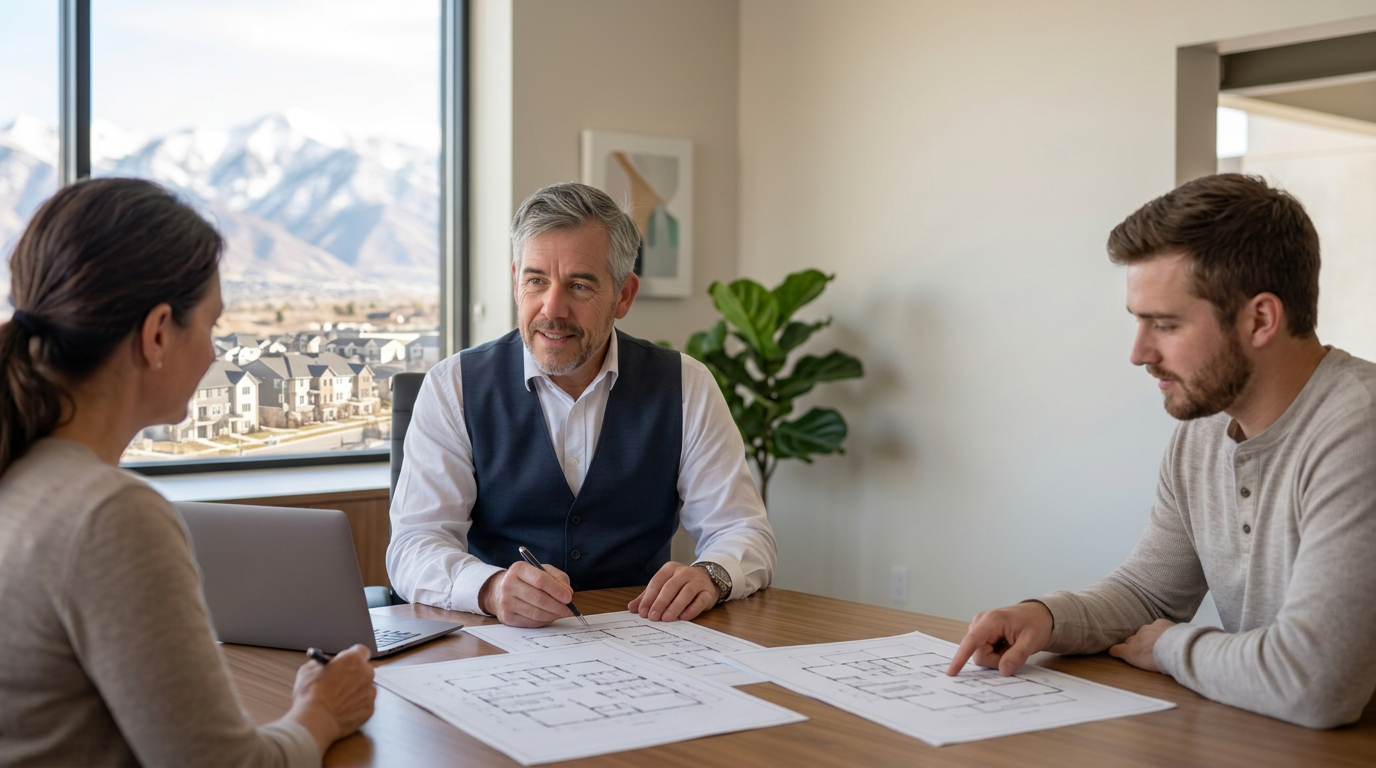
Tres “The Magic Mortgage Lender” Miller, Utah mortgage lender in his navy vest and white shirt, comparing condo and townhome floor plans with a young Utah couple, a townhome community and the Wasatch mountains through the window.
Tres “The Magic Mortgage Lender” Miller, Utah mortgage lender, comparing condo and townhome options with Utah buyers.

Executive summary

In Utah, the difference between a condominium and a townhome is legal, not architectural — and it decides your loan options, your insurance, and your monthly cost. This guide explains what you actually own in each structure, how condo project approval and warrantability work for FHA, VA, and conventional financing, which HOA documents to demand before you write an offer, and how to price two attached homes fairly once dues, assessments, and insurance are counted.

  • Condo and townhome describe ownership, not appearance — check the plat and title commitment.
  • Condo financing depends on the whole project: occupancy mix, delinquencies, litigation, and reserves.
  • FHA and VA buyers need an approved project; most townhome PUDs avoid that step.
  • Condos need an HO-6 policy sized to the association's master policy split.
  • HOA dues reduce your qualifying capacity dollar for dollar — include them from day one.
  • Reserve studies and board minutes are the best early warning of a special assessment.

The direct answer

In Utah, the difference between a condominium and a townhome is not about how the building looks — it is about what you legally own. With a condo you own the airspace inside your unit, and the land, structure, roof, and common areas are owned collectively by the association. With a townhome you typically own the structure and the land beneath it, and the association maintains shared exteriors, landscaping, and amenities. Two homes that look identical from the street can be recorded very differently, and that recording drives your financing, your insurance, and your monthly cost.

The practical consequence: condos are subject to project approval and warrantability review, which can limit your loan options and your future buyer pool. Townhomes recorded as planned-unit developments usually finance like a single-family home. Always confirm the legal form on the plat and title commitment — never on the listing description.

Executive summary

  • Ownership, not architecture, defines the difference: condo means airspace plus a share of common area; townhome usually means the structure plus the lot.
  • Condo financing depends on the whole project — owner-occupancy ratio, investor concentration, delinquent dues, litigation, and reserve funding all matter.
  • FHA and VA buyers need an approved condo project; townhomes in a planned-unit development generally do not face that hurdle.
  • Insurance differs: condos need an HO-6 walls-in policy behind the association's master policy; townhome owners often carry a full homeowners policy.
  • HOA dues, the master policy deductible, and reserve health belong in your affordability math from day one, not after you are under contract.
  • Along the Wasatch Front, attached homes are frequently the most attainable entry point — but resale liquidity depends on the project's financing eligibility.

A Utah example

Two buyers shop the same price point in Lehi. The first writes on a condo listed at $370,000 with $285 monthly dues. Underwriting pulls the project questionnaire and finds 38 percent of units are investor-owned and the association is midway through a siding assessment. Conventional financing is still possible through a portfolio option, but the FHA route the buyer planned on is off the table and the payment grows once the assessment is added.

The second buyer writes on a townhome at $395,000 with $145 monthly dues, recorded as a planned-unit development with a fee-simple lot. Financing runs like a detached home, the appraisal uses nearby townhome sales, and the insurance is a standard homeowners policy. The sticker price was higher, but the financing was simpler and the all-in monthly cost landed within roughly forty dollars of the condo. The lesson is that dues, assessments, and project eligibility — not list price — decide which attached home is actually cheaper.

Condo vs. townhome at a glance

FeatureCondominiumTownhome (typical PUD)
What you ownInterior airspace plus a share of common areaThe structure and the land beneath it
Financing reviewProject approval and warrantability requiredUsually underwritten like a single-family home
FHA / VAProject must appear on the approved listGenerally eligible without project approval
InsuranceMaster policy plus your HO-6 walls-in policyOften a full homeowners policy
Exterior upkeepAssociation handles roof, siding, groundsVaries — sometimes yours, sometimes the HOA's
Typical duesHigher, covering more shared systemsLower, covering fewer shared systems

Utah-specific considerations

Utah's Condominium Ownership Act and Community Association Act govern how these projects are created, governed, and funded, and they give buyers meaningful document rights before closing. Ask for the declaration and bylaws, the current budget, the most recent reserve study, meeting minutes for the past year, and a statement of any pending or planned special assessment. Reserve health is the single best predictor of whether your dues stay stable.

Local conditions matter too. Wasatch Front and Wasatch Back projects carry real snow-load, ice-dam, and roof-replacement exposure, and those costs land in the reserve budget. In Salt Lake, Utah, Davis, and Weber counties, many newer attached communities are recorded as planned-unit developments even when they are marketed as condos — confirm on the plat. Primary residences receive Utah's residential property tax exemption while second homes do not, so a nightly-rental or resort-area unit in Summit or Washington County carries both a bigger tax bill and narrower financing options.

Magic Mortgage Tip

Before you write an offer on any attached home, have your lender run the project questionnaire early — in the first few days, not during underwriting. A single answer about investor concentration, delinquent dues, or pending litigation can eliminate FHA, VA, or conventional eligibility. Knowing that upfront lets you negotiate, switch loan programs, or walk away before your earnest money and appraisal fee are at risk.

Myth vs. Fact

Myth: "If it shares a wall and has its own front door, it's a townhome."

Fact: Appearance tells you nothing about the legal form. Plenty of Utah homes that look like row townhomes are recorded as condominiums, and some stacked-flat buildings are recorded as planned-unit developments. The plat map and the title commitment are the only reliable sources — and they determine your loan options.

Common mistakes

  • Trusting the listing description instead of the plat and title commitment for the legal ownership form.
  • Qualifying on principal, interest, taxes, and insurance while leaving HOA dues out of the payment math.
  • Skipping the reserve study and minutes, then inheriting a special assessment months after closing.
  • Assuming FHA or VA financing works in any condo project without checking the approved list.
  • Buying an HO-6 policy that does not match the master policy's deductible and walls-in coverage split.
  • Ignoring rental caps and pet or parking restrictions that limit both your use and your future resale pool.

Today's action

Pick one condo and one townhome in your target area and price both fully — payment plus dues plus insurance — with the Mortgage Calculator and check your ceiling with the Home Affordability Calculator. Then request the association documents on the one you prefer and organize your file with the Utah Home Buyer Decision Worksheet before you write an offer.

Authoritative sources

  • Utah Code — Condominium Ownership Act and Community Association Act
  • U.S. Department of Housing and Urban Development — FHA condominium project approval
  • U.S. Department of Veterans Affairs — approved condominium projects
  • Fannie Mae and Freddie Mac — project eligibility and warrantability standards
  • Utah State Tax Commission — residential property tax exemption
  • Utah Division of Real Estate — consumer resources and licensee lookup

Myths vs. Facts

Myth

If it shares a wall and has its own front door, it's a townhome.

Fact

Appearance says nothing about the legal form. Many Utah row-style homes are recorded as condominiums, and the recorded form drives your financing.

Myth

A condo is always the cheaper option.

Fact

Once dues, HO-6 insurance, and assessment risk are counted, a slightly pricier townhome frequently costs about the same per month — or less.

Myth

FHA approval means VA approval.

Fact

FHA and VA maintain separate condominium approval lists, and approval by one agency does not carry over to the other.

Myth

The master policy covers everything inside my unit.

Fact

Many Utah master policies are bare-walls. Interior finishes, personal property, liability, and loss assessment come from your own HO-6 policy.

Common mistakes to avoid
  • ·Relying on the listing description instead of the plat and title commitment for the ownership form.
  • ·Budgeting principal, interest, taxes, and insurance while leaving HOA dues out of the math.
  • ·Skipping the reserve study and board minutes, then inheriting a special assessment.
  • ·Assuming FHA or VA financing works in any condo project without checking the approved list.
  • ·Buying an HO-6 policy that does not match the master policy's deductible and coverage split.
  • ·Overlooking rental caps, pet limits, and parking rules that affect use and resale.
Today's action

Price one condo and one townhome in your target area all-in — payment plus dues plus insurance — using the Mortgage Calculator and the Home Affordability Calculator. Then request the association documents on your favorite and organize your file with the Utah Home Buyer Decision Worksheet before writing an offer.

Utah Home Buyer Decision Worksheet (PDF)
Download PDF
Companion Video: Mortgage Insurance (PMI & MIP)
Watch video

Frequently Asked Questions

Ask the Authority
  • ?Is this Utah property recorded as a condominium or a fee-simple townhome?
  • ?Is this condo project approved for FHA or VA financing?
  • ?How much do the HOA dues lower the price range I qualify for?
  • ?What HOA documents should I review before I write an offer?
  • ?How much HO-6 coverage do I need behind a bare-walls master policy?

This asset is educational only and is not legal, tax, or personalized financial advice, and it is not a loan approval or commitment to lend. HOA rules, project approval status, insurance requirements, and Utah statutes change; verify current details with a Utah-licensed mortgage banker, the association, and your title company before deciding.

Keep learning

Related consumer guides
Related calculators
Related videos
Related knowledge assets
  • The Complete Utah Condo and Townhome Buying Guide
    Condominiums and townhomes can look identical from the street and underwrite very differently. This guide explains what you actually own, how FHA, VA, and conventional project approval works in Utah, how to read HOA budgets, reserve studies, and minutes like an underwriter, how master and HO-6 insurance fit together, and why HOA dues change how much home you qualify for.
  • The Complete Guide to Buying a Home in Utah
    Buying a home in Utah is a nine-step process with two decisions that drive everything else: the monthly payment you choose to live with and the loan program you qualify for. This guide walks the entire path — readiness, pre-approval, program selection, budgeting a real Utah payment, writing the offer on the state-approved contract, clearing due diligence and appraisal deadlines, and closing at a title company.
  • The Complete Utah First-Time Homebuyer Guide
    Buying a first home in Utah comes down to three aligned pieces: a qualifying credit profile, a manageable debt-to-income ratio, and documented cash for down payment and closing costs. This guide compares FHA, conventional, VA, USDA, and Utah Housing Corporation assistance side by side, breaks down what cash to close actually includes, walks the Utah purchase process from credit pull through closing, and flags the Utah-specific realities — county price differences, the residential property-tax exemption, builder incentives, and HOA and condo approval rules — that change the math.
Related resource centers
Tres Miller, Mortgage Banker, NMLS #217768

Written by

Tres Miller

Mortgage Banker · NMLS #217768 · U.S. Army veteran

Tres Miller is a Utah mortgage banker specializing in reverse mortgages and VA loans, with broader experience across Utah residential mortgage financing. A U.S. Army veteran, he has spent more than three decades helping Utah homeowners buy, finance, and protect their homes.

Specializing in reverse mortgages and VA loans, with broader work across Utah residential mortgage financing. Lending in Utah since 1995. Serving Utah County, Salt Lake County, Davis County, and all 29 Utah counties.

About TresProfessional historySchedule a consultation435-229-9797

Originally published September 7, 2026

Educational only. This asset does not constitute legal, tax, or financial advice. Programs, guidelines, and limits change frequently — verify current terms with a licensed Utah mortgage banker. Tres Miller serves homebuyers and homeowners throughout Utah — all 29 counties. Alpine, Highland, Cedar Hills, Mapleton, and Orem are a focus of our published content, not a limit on where mortgage services are provided. Tres Miller, Mortgage Banker, NMLS #217768 · JMJ Financial Group, Company NMLS #1866296 · Equal Housing Lender.

Ready to take the next step?

Talk to Tres — straight answers, real options, no pressure.