
Utah Homeownership Authority
TresThe Magic Mortgage LenderPowered by JMJ Financial Group
Divorce, Probate & Estate Planning · Knowledge Center · UHA-0042

What Happens to a Mortgage During Divorce in Utah?

A decree divides the house — only the lender can divide the debt. Refinance, assumption, or sale, compared for Utah couples.

By Tres MillerSeptember 4, 202610 min read
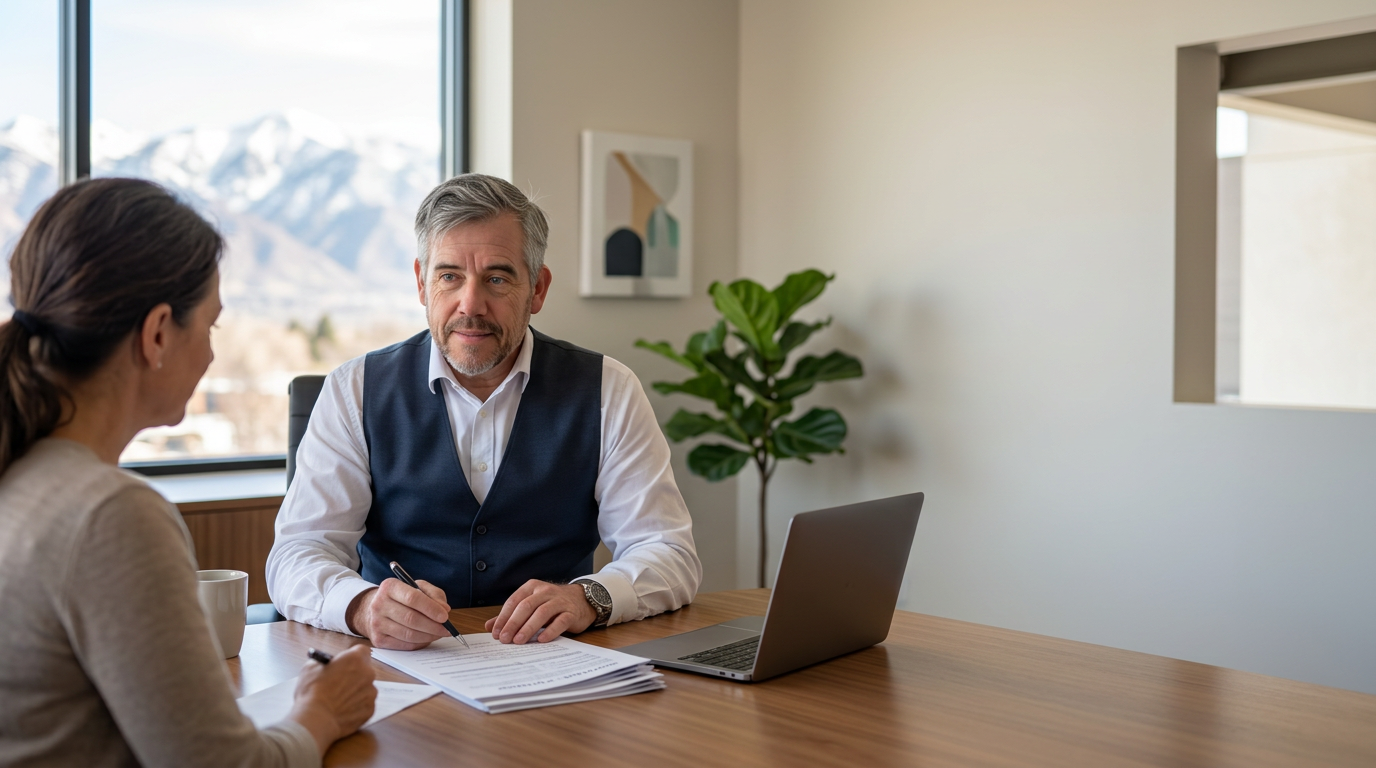
Tres “The Magic Mortgage Lender” Miller, Utah mortgage lender, reviewing mortgage and title documents with a Utah homeowner during a divorce consultation, with the Wasatch mountains visible through the office window.
Tres “The Magic Mortgage Lender” Miller, Utah mortgage lender, walking a Utah homeowner through refinance and assumption options during a divorce.

Executive summary

A Utah-specific walkthrough of what actually happens to a mortgage in a divorce: why a decree and a quitclaim deed do not remove a spouse from the note, how equitable distribution shapes the equity split, when a refinance beats a VA/FHA/USDA assumption, how support income is treated in qualifying, and the sequence that keeps both credit profiles intact through the transition.

  • A divorce decree binds the spouses, not the lender — the mortgage stays joint until it is refinanced, assumed, or paid off.
  • A quitclaim deed transfers ownership only. It does not remove anyone from the debt.
  • Utah divides marital property equitably, which is fair rather than automatically equal.
  • A refinance removes the departing spouse and can fund the equity buyout in one transaction.
  • VA, FHA, and USDA loans can often be assumed by a qualified spouse; conventional loans almost never can.
  • Support income usually needs a documented history and a required continuance period before it can be used to qualify.

The direct answer

A Utah divorce decree does not change the mortgage. The note is a contract with the lender, and a state court cannot rewrite it. Until the loan is refinanced, formally assumed, or paid off through a sale, both spouses remain fully liable for every payment — even the spouse who moved out, signed a quitclaim deed, and was awarded no interest in the home.

That leaves Utah couples three realistic paths for the marital home: one spouse refinances into their own name and buys out the other's share of equity; one spouse assumes the existing loan, which is possible on VA, FHA, and USDA loans and rare on conventional; or the home is sold and the net proceeds are divided. Everything else — quitclaim deeds, decree language, verbal agreements — changes who owns the property, not who owes the debt.

Executive summary

  • Title and debt are separate. A quitclaim deed transfers ownership; only the lender can release liability.
  • Utah is an equitable-distribution state, so the marital home and its equity are divided fairly — which is not automatically 50/50.
  • A refinance is the cleanest exit: it removes the departing spouse from the note and can fund the equity buyout in the same transaction.
  • VA, FHA, and USDA loans can often be assumed by a qualified spouse, preserving a low existing rate. A VA assumption by a non-veteran can tie up the veteran's entitlement.
  • Support payments can count as qualifying income — usually after a documented history and with a continuance requirement — and can also count against the paying spouse as a liability.
  • One late payment during the divorce damages both credit profiles and can disqualify the very refinance the decree requires.

A Utah example

A couple in Lehi owns a home worth $620,000 with a $360,000 mortgage balance at 3.25 percent. Equity is roughly $260,000. Their decree awards the home to one spouse, who owes the other half of the equity — about $130,000.

Refinancing $490,000 at current rates replaces a comfortable payment with a much larger one, and the loan must be sized to a single income. If the loan is FHA or VA, an assumption keeps the 3.25 percent rate on the existing $360,000 and the buyout is funded separately — from retirement assets, a second lien, or an offset of other marital property. Running both structures side by side, before the decree language is finalized, is what determines whether keeping the home is affordable at all.

Comparing the three paths

PathRemoves departing spouse?Keeps existing rate?Best when
RefinanceYesNoThe staying spouse qualifies alone and equity must be cashed out.
Loan assumption (VA/FHA/USDA)Yes, with a lender-approved release of liabilityYesThe existing rate is low and the buyout can be funded another way.
Sell the homeYes, at closingNoNeither spouse can carry the payment alone, or a clean break is the priority.

Magic Mortgage Tip

Get the mortgage answer before the decree is signed, not after. Decrees routinely order a refinance "within 90 days" without anyone checking whether the staying spouse can actually qualify on one income at today's rates. When the refinance fails, the couple is back in court — and back in attorney's fees. A pre-decree qualification review takes about an hour and it shapes the language your attorney writes.

Myth vs. Fact

Myth: "The judge awarded the house to my ex, so the mortgage is no longer mine."

Fact: The lender was not a party to the divorce. Until the loan is refinanced, assumed with a written release of liability, or paid off, a missed payment lands on both credit reports and both spouses can be pursued for the balance.

Common mistakes

  • Signing a quitclaim deed before the refinance or assumption is approved — giving up ownership while keeping the debt.
  • Writing a refinance deadline into the decree without a qualification review first.
  • Ignoring that support income usually needs a documented history and a required continuance period to be used for qualifying.
  • Assuming a conventional loan can be assumed. In nearly all cases it cannot.
  • Letting a payment go late during the separation and disqualifying the planned refinance.
  • Using an outdated value instead of a current appraisal to set the equity buyout.
  • Overlooking the VA entitlement consequences when a non-veteran spouse assumes a VA loan.

Today's action

Pull your current mortgage statement and confirm the loan type — VA, FHA, USDA, or conventional — then request a written payoff and ask whether the loan is assumable. Bring that, plus a realistic single-income budget, to a Utah-licensed mortgage banker before your attorney drafts the property section of the decree. Run the numbers with the Home Equity Calculator and the Mortgage Calculator.

Authoritative sources

  • Utah Courts — divorce and property division self-help resources
  • Utah Code Title 30 — Husband, Wife, and Family Relations
  • U.S. Department of Veterans Affairs — loan assumption and entitlement
  • HUD Handbook 4000.1 — FHA assumptions and creditworthiness review
  • Consumer Financial Protection Bureau — mortgages and divorce

Myths vs. Facts

Myth

The judge awarded the house to my ex, so the mortgage is no longer mine.

Fact

The lender was not a party to the divorce. Until the loan is refinanced, assumed with a written release of liability, or paid off, both spouses remain liable.

Myth

Signing a quitclaim deed gets me off the loan.

Fact

A quitclaim moves title. The note is untouched — you can end up owing on a home you no longer own.

Myth

Utah splits everything exactly in half.

Fact

Utah uses equitable distribution. Courts weigh contributions, length of marriage, and circumstances, so the equity split can be uneven.

Myth

We can just keep the low rate by leaving the loan alone.

Fact

Leaving it alone leaves both spouses liable. Preserving the rate legitimately means a lender-approved assumption with a release of liability.

Common mistakes to avoid
  • ·Signing a quitclaim deed before the refinance or assumption is approved.
  • ·Writing a refinance deadline into the decree without a qualification review first.
  • ·Assuming a conventional loan can be assumed — it almost never can.
  • ·Counting alimony or child support as income without the required documented history and continuance.
  • ·Letting a payment go late during the separation and disqualifying the planned refinance.
  • ·Setting the equity buyout from an outdated value instead of a current appraisal.
  • ·Overlooking VA entitlement consequences when a non-veteran spouse assumes a VA loan.
Today's action

Pull your current mortgage statement, confirm the loan type, and ask the servicer in writing whether the loan is assumable. Bring that, a current value estimate, and a single-income budget to a Utah-licensed mortgage banker before your attorney drafts the property section of the decree.

Utah Home Buyer Decision Worksheet (PDF)
Download PDF
Companion Video: Why Refinance?
Watch video

Frequently Asked Questions

Ask the Authority
  • ?What happens to my mortgage in a Utah divorce?
  • ?Does a quitclaim deed remove me from the mortgage?
  • ?Can I assume my spouse's FHA or VA loan after divorce?
  • ?How is a home equity buyout calculated in Utah?
  • ?Can I use alimony to qualify for a refinance?

This asset is educational only and is not legal, tax, or personalized financial advice, and it is not a loan approval or commitment to lend. Divorce law, property division, loan assumption rules, entitlement treatment, and qualifying guidelines change; verify current details with a Utah family law attorney, your loan servicer, and a Utah-licensed mortgage banker before deciding.

Keep learning

Related consumer guides
Related calculators
Related videos
Related knowledge assets
  • The Complete Utah Divorce and Mortgage Guide
    A Utah divorce decree does not remove a spouse from the mortgage — only the lender can. Utah couples have three paths for the marital home: refinance and buy out equity, assume the existing VA/FHA/USDA loan, or sell the home. The most common expensive mistake is signing a quitclaim without a plan to release the departing spouse from the mortgage.
  • How Much Should Utah Homeowners Keep in Emergency Savings?
    Utah homeowners need two separate reserves: an emergency fund of three to six months of total living expenses, and a home repair reserve of roughly one percent of the home's value each year. This guide sizes both against real Utah conditions — variable self-employment income, hard water and short water-heater life, freeze-thaw roof wear, and escrow analyses that change a fixed-rate payment — and explains how documented reserves also strengthen a mortgage file.
  • How Property Tax Assessments Are Calculated in Utah
    A Utah-specific walkthrough of how a property tax bill is actually built: how county assessors set January 1 market values, why a primary residence is taxed on only 55 percent of value, how certified rates and Truth in Taxation hearings constrain revenue, how to read the summer valuation notice, how to appeal to the county Board of Equalization before the deadline, which relief programs require an application, and how an assessment change flows into an escrowed mortgage payment.
Related resource centers
Tres Miller, Mortgage Banker, NMLS #217768

Written by

Tres Miller

Mortgage Banker · NMLS #217768 · U.S. Army veteran

Tres Miller is a Utah mortgage banker specializing in reverse mortgages and VA loans, with broader experience across Utah residential mortgage financing. A U.S. Army veteran, he has spent more than three decades helping Utah homeowners buy, finance, and protect their homes.

Specializing in reverse mortgages and VA loans, with broader work across Utah residential mortgage financing. Lending in Utah since 1995. Serving Utah County, Salt Lake County, Davis County, and all 29 Utah counties.

About TresProfessional historySchedule a consultation435-229-9797

Originally published September 4, 2026

Educational only. This asset does not constitute legal, tax, or financial advice. Programs, guidelines, and limits change frequently — verify current terms with a licensed Utah mortgage banker. Tres Miller serves homebuyers and homeowners throughout Utah — all 29 counties. Alpine, Highland, Cedar Hills, Mapleton, and Orem are a focus of our published content, not a limit on where mortgage services are provided. Tres Miller, Mortgage Banker, NMLS #217768 · JMJ Financial Group, Company NMLS #1866296 · Equal Housing Lender.

Ready to take the next step?

Talk to Tres — straight answers, real options, no pressure.