Utah Homeownership Authority
Tres“The Magic Mortgage Lender”Powered by JMJ Financial Group
VA Loans · Knowledge Center · UHA-0092

Buying a Condo With a VA Loan in Alpine, Utah: How Project Approval Works

The VA approves the condo project, not the unit. Here is how project approval works in Alpine — and what it means for zero-down financing.

By Tres MillerOctober 13, 20268 min read
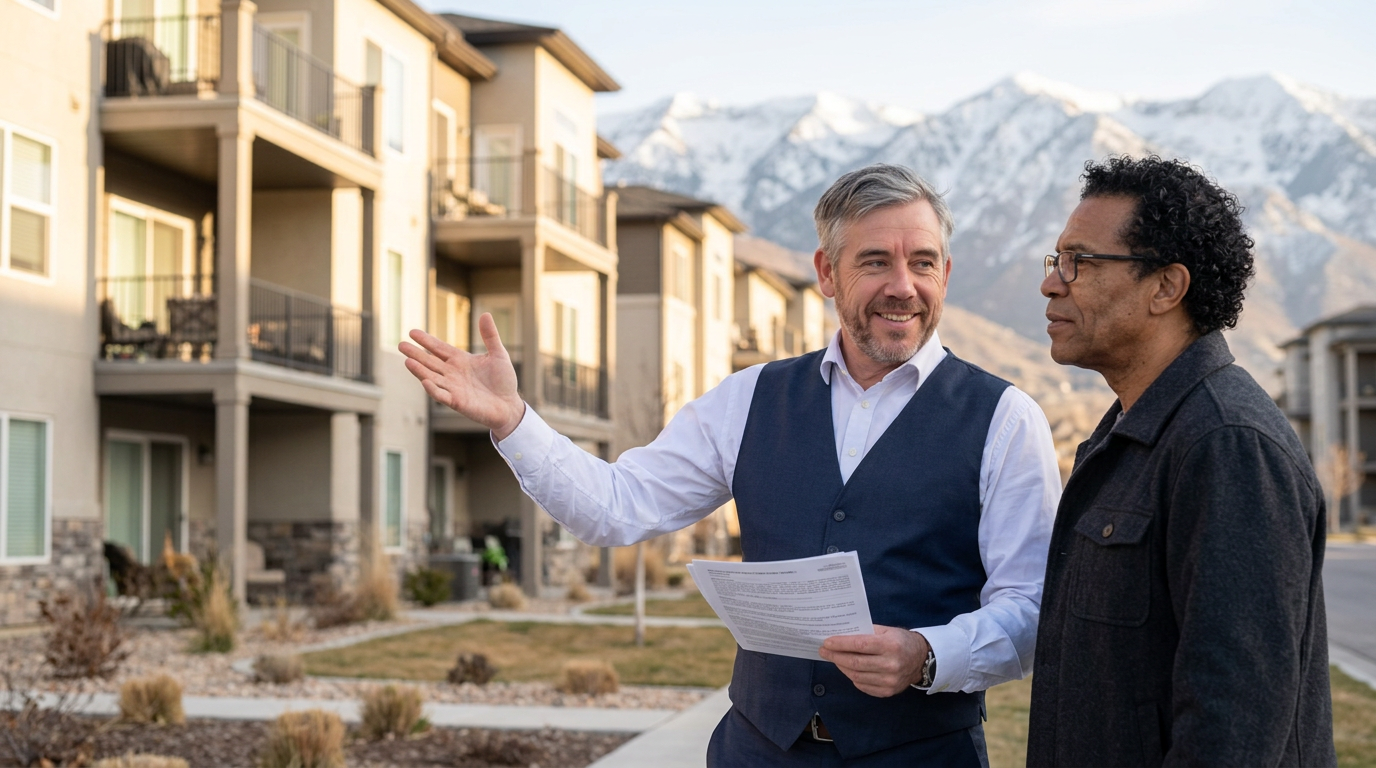
Tres “The Magic Mortgage Lender” Miller in his navy vest and white shirt walking a veteran homebuyer through VA condo project approval outside a condominium building in Alpine, Utah.
Tres “The Magic Mortgage Lender” Miller walks through how VA condo project approval works for buyers in Alpine, Utah.

Executive summary

A Alpine, Utah guide to buying a condo with a VA loan: how VA project approval works, what lenders check, and how zero-down financing applies inside approved projects.

  • The VA approves the condo project, not the individual unit.
  • Your lender verifies project approval before underwriting starts.
  • Owner-occupancy ratios, insurance, reserves, and litigation are the core checks.
  • Zero-down VA financing still applies inside an approved project.
  • HOA dues count in your debt-to-income ratio and can shrink buying power.
  • A rejected project can sometimes be remedied, but rarely on a tight timeline.

The direct answer

Yes — a veteran can buy a condo in Alpine, Utah with a VA loan and zero down, as long as the specific condominium project is VA-approved. The VA does not approve individual units; it approves the entire project, and your lender verifies that approval before underwriting begins.

Approval is a project-level check on owner-occupancy ratios, insurance coverage, financial reserves, litigation, and transfer rules. If the project clears it, the loan proceeds like any other VA purchase — same entitlement, same funding fee, same zero-down advantage.

Executive summary

  • The VA approves the condo project, not the individual unit.
  • Your lender verifies project approval before underwriting starts.
  • Owner-occupancy ratios, insurance, reserves, and litigation are the core checks.
  • Zero-down VA financing still applies inside an approved project.
  • Condo HOA dues count in your debt-to-income ratio.
  • A rejected project can sometimes be remedied, but rarely on a tight timeline.

How VA condo project approval actually works

Two paths can put a project on the VA's approved list. The project may already hold approval — often because an earlier VA or FHA buyer financed there — or your lender submits a project review on your behalf. The review examines the association's documents: the declaration, bylaws, budget, reserve study, master insurance policy, and the current ratio of owner-occupied units to rentals.

The VA's approval standards are broadly similar to FHA's, and many lenders maintain their own additional overlay on condo lending. That means a project can clear the VA test and still fail a specific lender's requirements — one more reason to confirm approval with your lender, not with the seller or the HOA sign at the entrance.

What the project review looks for

CheckWhat usually fails a project
Owner-occupancy ratioToo many units rented — common in investor-heavy buildings
InsuranceGaps in master policy coverage or no builder's-risk completion
Budget and reservesUnderfunded reserves or deferred maintenance on record
LitigationActive construction-defect or HOA lawsuits
Legal phaseProject still in a partial or unsold completion phase
Transfer and rental rulesRestrictions that conflict with program requirements

What is specific to Alpine

Alpine's condo and townhome inventory is smaller than its single-family market, and much of it sits at price points where zero-down VA financing is genuinely competitive. The gate is not the price — it is whether the specific project carries VA approval.

In Alpine, several newer townhome communities are platted as Planned Unit Developments, which lenders process differently than a traditional condo project. Confirm how the property is titled before you assume a project review is simple.

Confirm eligibility in the Alpine VA eligibility guide, and see how first-time and repeat use work in the Alpine VA entitlement guide.

Costs beyond the zero-down advantage

The VA funding fee works exactly as it does on a single-family purchase: one-time, based on the loan amount, commonly financed, with exemptions for qualifying veterans. What changes on a condo is the monthly math — HOA dues are added to your debt-to-income ratio, so a high dues structure can shrink buying power even when the price looks comfortable.

Closing costs are also project-flavored: HOA transfer and estoppel fees, and prorated dues, show up on the settlement statement. The seller can still pay normal closing costs plus up to 4% in concessions, so negotiate those numbers into the offer rather than assuming them.

Common misunderstandings about VA condo purchases

The most common myth is that VA loans cannot buy condos at all — they can, inside an approved project. A second myth is that FHA approval automatically means VA approval; the lists are maintained separately, and one does not guarantee the other. A third is that a unit inside a rejected project is always dead — approval can sometimes be obtained, but lenders rarely count on that inside a Utah contract timeline.

How Tres would evaluate this

A Alpine veteran finds a condo in the right price range and asks whether zero down still works. Tres first confirms the buyer's Certificate of Eligibility, then immediately orders a project approval check — because that single answer decides whether the offer is worth writing at all. Only after the project clears does he size the payment with HOA dues included.

This is an illustrative decision framework, not a description of a specific client or completed transaction.

What to verify before you decide

  • Current VA project approval status for the specific association.
  • Whether the lender has its own additional condo requirements.
  • HOA dues, transfer fees, and prorated dues at closing.
  • The association's budget, reserve study, and insurance certificate.
  • Your funding-fee percentage and exemption status.
  • That the appraisal is likely to support the price.

Verify current VA condo project requirements with the U.S. Department of Veterans Affairs and a Utah-licensed mortgage banker.
Myths vs. Facts

Myth

VA loans cannot buy condos.

Fact

They can, inside a VA-approved condominium project.

Myth

FHA approval automatically means VA approval.

Fact

The approval lists are maintained separately; one does not guarantee the other.

Myth

Project approval is a one-time thing.

Fact

Rules and project circumstances change, so approval is re-verified with every loan.

Myth

The HOA sign at the entrance settles the question.

Fact

Only the lender's current project review does — confirm with your lender.

Myth

HOA dues are just a lifestyle cost.

Fact

Dues are part of your debt-to-income ratio and directly affect buying power.

Common mistakes to avoid
  • ·Writing an offer before confirming project approval.
  • ·Assuming a prior VA buyer's approval still holds today.
  • ·Ignoring HOA transfer and estoppel fees at closing.
  • ·Not budgeting HOA dues into the debt-to-income ratio.
  • ·Skipping the association's budget, reserve study, and insurance certificate.
  • ·Assuming the seller must cover costs because the loan is VA.
Today's action

Before your next Alpine condo offer, have your lender confirm the project's VA approval status and pull the association's budget and insurance certificate.

Utah VA Buyer Cash-to-Close Worksheet (PDF)
Download PDF

Frequently Asked Questions

Ask the Authority
  • ?Can I buy a condo in Alpine with a VA loan?
  • ?How is VA condo project approval checked?
  • ?What happens if the condo project is not VA-approved?
  • ?Do HOA dues count against my VA loan qualification?
  • ?Can the seller pay closing costs on a VA condo purchase?

This asset is educational only and is not legal, tax, VA-benefit, or personalized financial advice, and it is not a loan approval or commitment to lend. VA condo project-approval, funding-fee, and concession rules change; verify current requirements with the VA and a Utah-licensed mortgage banker.

This article sits inside our VA loans coverage. For the full picture, start at the Utah VA loan specialist page, browse the VA Loan Resource Center, read about Tres Miller, or schedule a 15-minute consultation.

Related reading: eligibility and your COE, entitlement, VA appraisals, the funding fee, and the IRRRL streamline refinance.

Keep learning

Related consumer guides
Related calculators
  • Utah VA Loan Calculator
    Estimate a zero-down Utah VA loan payment, model the VA funding fee, and compare VA against FHA and conventional financing.
  • Utah Mortgage Calculator
    Estimate a Utah mortgage payment including principal, interest, taxes, and insurance.
Related knowledge assets
  • VA Loan Eligibility in Alpine, Utah: Who Qualifies and What Documents Matter
    Who qualifies for a VA loan in Alpine, Utah and exactly which documents a veteran should have ready before making an offer — the Certificate of Eligibility, DD-214 or Statement of Service, Guard and Reserve records, disability award letters — plus how entitlement, the funding fee, occupancy, and the VA appraisal behave in one of Utah County’s higher-priced markets.
  • VA Loan Entitlement in Alpine, Utah: How First-Time and Repeat Use Works
    How VA entitlement works for an Alpine, Utah buyer — what full entitlement means for a first-time user, how remaining entitlement is calculated for repeat use, when restoration is required, and how the funding fee, occupancy rules, and the Utah County loan limit shape the down payment.
  • VA Closing Costs in Alpine, Utah: What a Veteran Should Budget Before Closing
    An Alpine, Utah guide to VA closing costs: what a veteran should budget beyond zero-down financing, where the money goes, which fees the VA restricts, and how seller-paid costs change the number.
  • The Complete Utah Condo and Townhome Buying Guide
    Condominiums and townhomes can look identical from the street and underwrite very differently. This guide explains what you actually own, how FHA, VA, and conventional project approval works in Utah, how to read HOA budgets, reserve studies, and minutes like an underwriter, how master and HO-6 insurance fit together, and why HOA dues change how much home you qualify for.
Tres Miller, Mortgage Banker, NMLS #217768

Written by

Tres Miller

Mortgage Banker · NMLS #217768 · U.S. Army veteran

Tres Miller is a Utah mortgage banker specializing in reverse mortgages and VA loans, with broader experience across Utah residential mortgage financing. A U.S. Army veteran, he has spent more than three decades helping Utah homeowners buy, finance, and protect their homes.

Specializing in reverse mortgages and VA loans, with broader work across Utah residential mortgage financing. Lending in Utah since 1995. Serving Utah County, Salt Lake County, Davis County, and all 29 Utah counties.

About TresProfessional historySchedule a consultation435-229-9797

Originally published October 13, 2026

Educational only. This asset does not constitute legal, tax, or financial advice. Programs, guidelines, and limits change frequently — verify current terms with a licensed Utah mortgage banker. Tres Miller serves homebuyers and homeowners throughout Utah — all 29 counties. Alpine, Highland, Cedar Hills, Mapleton, and Orem are a focus of our published content, not a limit on where mortgage services are provided. Tres Miller, Mortgage Banker, NMLS #217768 · JMJ Financial Group, Company NMLS #1866296 · Equal Housing Lender.

Ready to take the next step?

Talk to Tres — straight answers, real options, no pressure.