Utah Homeownership Authority
Tres“The Magic Mortgage Lender”Powered by JMJ Financial Group
VA Loans · Knowledge Center · UHA-0073

How to Make a Strong VA Offer in Highland, Utah Without Giving Up Key Protections

Winning Highland offers compete on certainty — full pre-approval, clean terms, and smart timelines — not on waiving the protections that keep VA buyers safe.

By Tres MillerOctober 2, 20268 min read
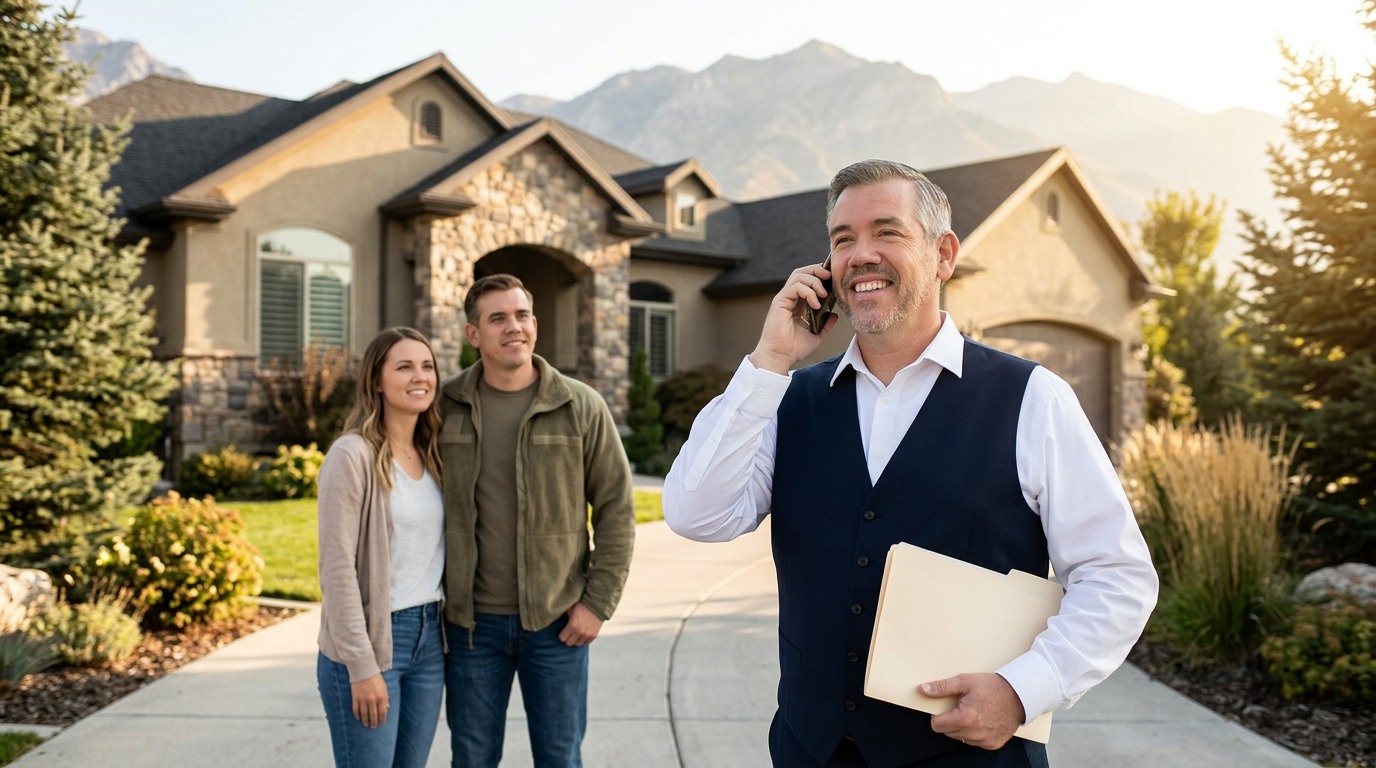
Tres “The Magic Mortgage Lender” Miller in his navy vest and white shirt reviewing an offer folder in front of a Highland, Utah home.
Tres “The Magic Mortgage Lender” Miller helps Highland, Utah VA buyers write strong offers that keep their protections.

Executive summary

A Highland, Utah guide to writing a competitive VA offer: what actually makes an offer strong, which protections to keep, how to handle seller concerns about VA loans, and what to verify before you write.

  • Compete on certainty: full pre-approval, verified funds, and a reachable lender.
  • Keep the appraisal contingency — the VA escape clause protects your earnest money.
  • Keep the inspection; shorten timelines instead of waiving protections.
  • Meaningful earnest money and a seller-friendly closing date strengthen the offer.
  • Seller concerns about VA loans are answered with presentation, not concessions.

The direct answer

A strong VA offer in Highland, Utah is built on certainty, not on giving up protections. The buyers who win keep their appraisal, inspection, and financing contingencies — and compete instead with a full pre-approval (not a pre-qualification), meaningful earnest money, a realistic closing timeline, seller-concession requests kept within reason, and a clean, complete contract package.

The VA loan itself is not a weakness. The VA escape clause and appraisal protections exist to protect the buyer, and a well-presented VA offer can beat a conventional one when the seller trusts it will close.

Executive summary

  • Compete on certainty: full pre-approval, verified funds, and a lender who answers the phone.
  • Keep the appraisal contingency — the VA escape clause protects your earnest money.
  • Keep the inspection; adjust timelines instead of waiving protections.
  • Offer meaningful earnest money and a closing date that fits the seller.
  • Ask for seller concessions only when the numbers genuinely require them.
  • A cover letter from the lender explaining the VA process can neutralize seller concerns.
  • Price the offer from comparable sales, not from emotion.

What makes an offer strong — and what to keep

LeverStrong moveAvoid
FinancingFull pre-approval with verified income, assets, and COEA quick online pre-qualification letter
AppraisalKeep the VA escape clause; plan for a low-value scenarioPromising to cover any appraisal gap blindly
InspectionKeep it; shorten the window instead of waivingWaiving inspection on an unfamiliar property
Earnest moneyAn amount that shows commitment, within your budgetMoney you cannot afford to risk
TimelineA closing date matched to the seller's needsPromising a date the loan cannot meet

What is specific to Highland

Highland's newer custom construction and family neighborhoods attract move-up buyers, and desirable listings can draw multiple offers. Sellers compare offers on certainty: the strength of the buyer's financing, the size of the earnest money, and how few surprises the contract contains.

In Highland's competitive pockets, the offers that win are usually the ones that remove doubt — full pre-approval, flexible closing, and clear communication — not the ones that strip out the buyer's own protections.

Confirm eligibility and documents in the Highland VA eligibility guide, and understand the Highland VA appraisal process before writing an offer.

Handling seller concerns about VA loans

Some sellers still believe VA loans are slow, that the VA forces sellers to pay the buyer's costs, or that VA appraisals are deal-killers. None of these are accurate today: VA loans close on timelines comparable to conventional loans, seller-paid costs are negotiated — never required beyond a small set of fees — and the appraisal's minimum property requirements mostly overlap with what any buyer's inspector would flag.

The practical counter is presentation: a complete pre-approval package, a lender who calls the listing agent directly, and a contract with clean terms. That is what turns a VA offer from a question mark into the safe choice.

How Tres would evaluate this

A Highland veteran finds a home they love and expects competition. Tres reviews three things before the offer goes in: whether the buyer's pre-approval is fully documented so the listing agent can verify it in one call, which protections must stay in the contract (appraisal, inspection, financing) and which timelines can flex, and how the price compares to recent Highland sales so the offer is strong without being reckless.

This is an illustrative decision framework, not a description of a specific client or completed transaction.

What to verify before you decide

  • That your pre-approval is fully documented — income, assets, and Certificate of Eligibility.
  • How the home's price compares to recent comparable sales in Highland.
  • Which contingencies you are keeping, and the timeline for each.
  • How much earnest money you can commit comfortably.
  • What closing date works for the seller, and whether your loan can meet it.
  • Whether your lender will speak directly with the listing agent.

Verify current VA loan, appraisal, and contract rules with the U.S. Department of Veterans Affairs and a Utah-licensed mortgage banker.
Myths vs. Facts

Myth

VA buyers must waive the appraisal to compete.

Fact

The VA escape clause protects your earnest money, and strong offers keep it while competing on certainty and terms.

Myth

Sellers will not accept VA loans.

Fact

VA loans close on timelines comparable to conventional loans; a well-presented VA offer is often the safer choice for a seller.

Myth

The seller must pay the VA buyer's closing costs.

Fact

Seller concessions are negotiated, never required beyond a small set of VA-restricted fees.

Myth

Waiving the inspection makes the offer stronger.

Fact

It mostly makes the buyer's position weaker. Shortening the inspection window achieves the same seller benefit with far less risk.

Myth

The highest price always wins.

Fact

Sellers weigh certainty — financing strength, earnest money, and clean terms — alongside price.

Common mistakes to avoid
  • ·Offering with only a quick pre-qualification letter.
  • ·Waiving the appraisal or inspection contingency to look competitive.
  • ·Promising a closing date the loan cannot meet.
  • ·Asking for seller concessions the numbers do not require.
  • ·Letting emotion set the price instead of comparable sales.
  • ·Choosing a lender the listing agent cannot reach.
Today's action

Before your next Highland offer, confirm your pre-approval is fully documented, decide which protections stay in the contract, and review recent comparable sales with your agent.

Utah VA Buyer Cash-to-Close Worksheet (PDF)
Download PDF

Frequently Asked Questions

Ask the Authority
  • ?How do I compete with cash offers in Highland?
  • ?Should I waive the appraisal contingency?
  • ?What earnest money is normal in Highland?
  • ?Do sellers dislike VA loans?
  • ?How fast can a VA loan close?

This asset is educational only and is not legal, tax, VA-benefit, or personalized financial advice, and it is not a loan approval or commitment to lend. VA funding-fee, entitlement, appraisal, closing-cost, and concession rules change; verify current requirements with the VA and a Utah-licensed mortgage banker.

This article sits inside our VA loans coverage. For the full picture, start at the Utah VA loan specialist page, browse the VA Loan Resource Center, read about Tres Miller, or schedule a 15-minute consultation.

Related reading: eligibility and your COE, entitlement, VA appraisals, the funding fee, and the IRRRL streamline refinance.

Keep learning

Related consumer guides
Related calculators
  • Utah VA Loan Calculator
    Estimate a zero-down Utah VA loan payment, model the VA funding fee, and compare VA against FHA and conventional financing.
  • Utah Mortgage Calculator
    Estimate a Utah mortgage payment including principal, interest, taxes, and insurance.
Related knowledge assets
  • VA Loan Eligibility in Highland, Utah: Who Qualifies and What Documents Matter
    Who is eligible for a VA loan in Highland, Utah and exactly which documents a veteran should prepare before applying — the Certificate of Eligibility, DD-214 or Statement of Service, NGB-22 and point statements, disability award letters — plus how entitlement, the funding fee, occupancy, and the VA appraisal behave in northern Utah County.
  • VA Appraisals in Highland, Utah: What Buyers and Sellers Should Expect
    A practical Highland, Utah guide to the VA appraisal: who orders it, what minimum property requirements mean, what happens when value comes in low, and how the Reconsideration of Value process works.
  • The Complete Utah VA Loan Guide
    The VA home loan is the strongest financing benefit available to eligible Utah veterans, service members, and qualifying surviving spouses: no required down payment within entitlement, no monthly mortgage insurance, and a reusable lifetime benefit. This guide covers how the guaranty works, who qualifies, what a Utah VA purchase actually costs, funding-fee exemptions, appraisal and property requirements, entitlement reuse and assumptions, and the Utah-specific details that decide real transactions.
Tres Miller, Mortgage Banker, NMLS #217768

Written by

Tres Miller

Mortgage Banker · NMLS #217768 · U.S. Army veteran

Tres Miller is a Utah mortgage banker specializing in reverse mortgages and VA loans, with broader experience across Utah residential mortgage financing. A U.S. Army veteran, he has spent more than three decades helping Utah homeowners buy, finance, and protect their homes.

Specializing in reverse mortgages and VA loans, with broader work across Utah residential mortgage financing. Lending in Utah since 1995. Serving Utah County, Salt Lake County, Davis County, and all 29 Utah counties.

About TresProfessional historySchedule a consultation435-229-9797

Originally published October 2, 2026

Educational only. This asset does not constitute legal, tax, or financial advice. Programs, guidelines, and limits change frequently — verify current terms with a licensed Utah mortgage banker. Tres Miller serves homebuyers and homeowners throughout Utah — all 29 counties. Alpine, Highland, Cedar Hills, Mapleton, and Orem are a focus of our published content, not a limit on where mortgage services are provided. Tres Miller, Mortgage Banker, NMLS #217768 · JMJ Financial Group, Company NMLS #1866296 · Equal Housing Lender.

Ready to take the next step?

Talk to Tres — straight answers, real options, no pressure.