Utah Homeownership Authority
Tres“The Magic Mortgage Lender”Powered by JMJ Financial Group
VA Loans · Knowledge Center · UHA-0064

VA Funding Fee in Cedar Hills, Utah: Who Pays It and Who May Be Exempt

The funding fee is a one-time cost on most VA loans — and some Cedar Hills veterans do not pay it at all.

By Tres MillerSeptember 12, 20268 min read
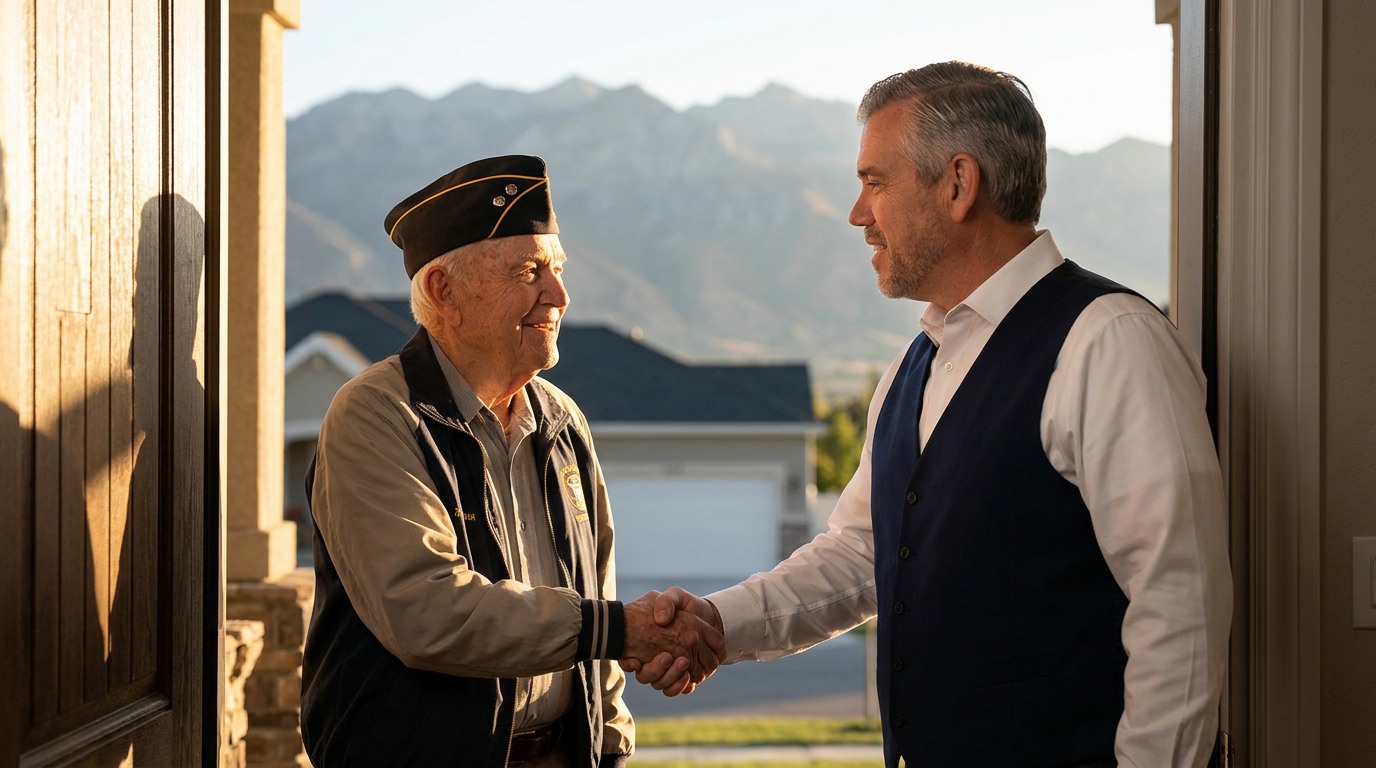
Tres “The Magic Mortgage Lender” Miller in his navy vest and white shirt talking with veteran homeowners on the porch of a Cedar Hills, Utah home.
Tres “The Magic Mortgage Lender” Miller helps Cedar Hills, Utah veterans understand the VA funding fee and who may be exempt.

Executive summary

A practical Cedar Hills, Utah guide to the VA funding fee: what it is, how the percentage is set, when it can be financed, who is exempt, and how to verify the exemption before closing.

  • The funding fee is a one-time charge on most VA loans, not monthly mortgage insurance.
  • The percentage depends on first or subsequent use, down payment, and loan type.
  • Most borrowers finance the fee into the loan.
  • Veterans with qualifying service-connected disability compensation are generally exempt.
  • The exemption is verified on the Certificate of Eligibility.
  • A down payment of five percent or more can lower the fee percentage.

The direct answer

Most veterans using a VA loan in Cedar Hills, Utah pay a one-time VA funding fee. The fee is a percentage of the loan amount, and the percentage depends on whether this is a first or subsequent use, the size of any down payment, and the loan type. It can be paid in cash at closing or financed into the loan.

Some borrowers do not pay the fee at all. Veterans receiving VA compensation for a service-connected disability, certain surviving spouses, and certain active-duty Purple Heart recipients are generally exempt. The Certificate of Eligibility shows whether the exemption applies.

Executive summary

  • The funding fee is a one-time charge that supports the VA loan program; it is not mortgage insurance.
  • The percentage depends on first or subsequent use, down payment, and loan type.
  • Most borrowers finance the fee into the loan instead of paying it in cash.
  • Financing the fee raises the loan balance and the monthly payment slightly.
  • Veterans with qualifying service-connected disability compensation are generally exempt.
  • The exemption is verified on the Certificate of Eligibility before closing.
  • A down payment of five percent or more can lower the fee percentage.

How the fee is structured

SituationGeneral effect on the feeWhat to confirm
First use, zero downStandard first-use percentageCurrent VA fee schedule
Subsequent use, zero downHigher percentage than first usePrior VA loan history on the COE
Five percent or more downLower percentage tierExact down-payment amount in the contract
Exempt borrowerNo funding fee chargedExemption shown on the COE
Financed vs. cashFinancing raises balance and paymentLoan estimate shows which was chosen

Percentages are set by the VA and change from time to time. Confirm the current schedule with the U.S. Department of Veterans Affairs and your lender before relying on any figure.

What is specific to Cedar Hills

Cedar Hills is a planned foothill community where many homes carry homeowners-association dues. The funding fee itself is unaffected by HOA dues, but the dues count in the lender's payment calculation, so the combined picture — financed fee plus HOA dues — is what a Cedar Hills buyer should review before deciding how much cash to bring to closing.

Confirm eligibility and documents in the Cedar Hills VA eligibility guide, then review Cedar Hills entitlement before treating the fee question as settled.

Who may be exempt

The most common exemption applies to veterans who receive VA compensation for a service-connected disability. Certain surviving spouses of veterans who died in service or from a service-connected disability may also be exempt, as may active-duty service members who hold a Purple Heart. Eligibility for the exemption is not assumed — it is verified through the Certificate of Eligibility.

If a disability claim is pending near closing, ask the lender how the fee will be handled and whether a refund is possible if the exemption is later confirmed. Compare the payment difference in the VA Loan Calculator.

How Tres would evaluate this

A Cedar Hills veteran is deciding whether to finance the funding fee or pay it in cash. Tres lays out three numbers side by side: the fee amount itself, the monthly-payment difference if it is financed, and the cash the household keeps in reserve if it is financed. In Cedar Hills, review the financed funding fee together with HOA dues so the total monthly obligation is clear before you offer. The decision is made only after the COE confirms whether any exemption applies.

This is an illustrative decision framework, not a description of a specific client or completed transaction.

What to verify before you decide

  • Whether your Certificate of Eligibility shows a funding-fee exemption.
  • Whether this is a first or subsequent use of your VA benefit.
  • The current VA funding-fee percentage for your loan type and down payment.
  • Whether the fee will be financed or paid in cash, as shown on the loan estimate.
  • The monthly-payment difference between financing and paying the fee in cash.
  • How a down payment of five percent or more would change the fee.

Verify current VA funding-fee percentages and exemption rules with the U.S. Department of Veterans Affairs and a Utah-licensed mortgage banker.
Myths vs. Facts

Myth

The funding fee is monthly mortgage insurance.

Fact

It is a one-time fee charged at closing or financed into the loan; VA loans have no monthly mortgage insurance premium.

Myth

Every veteran pays the funding fee.

Fact

Veterans receiving qualifying service-connected disability compensation and certain surviving spouses are generally exempt.

Myth

The fee is the same in every situation.

Fact

The percentage varies with first or subsequent use, down payment, and loan type.

Myth

The exemption is automatic.

Fact

It must be verified on the Certificate of Eligibility before closing.

Myth

Financing the fee is free.

Fact

Financing raises the loan balance and the monthly payment slightly.

Common mistakes to avoid
  • ·Assuming the exemption applies without checking the COE.
  • ·Confusing the funding fee with monthly mortgage insurance.
  • ·Ignoring the payment difference when the fee is financed.
  • ·Missing the lower fee tier that comes with five percent down.
  • ·Relying on an outdated fee percentage.
  • ·Forgetting to review the fee on the loan estimate.
Today's action

Pull your Certificate of Eligibility, confirm whether a funding-fee exemption applies, and compare the financed versus cash fee on the VA Loan Calculator before writing a Cedar Hills offer.

Utah VA Buyer Cash-to-Close Worksheet (PDF)
Download PDF

Frequently Asked Questions

Ask the Authority
  • ?Am I exempt from the VA funding fee?
  • ?How much would the funding fee be on a Cedar Hills home?
  • ?Should I finance the fee or pay it in cash?
  • ?Would five percent down lower my fee?
  • ?How do I verify the exemption on my COE?

This asset is educational only and is not legal, tax, VA-benefit, or personalized financial advice, and it is not a loan approval or commitment to lend. VA funding-fee, entitlement, appraisal, closing-cost, and concession rules change; verify current requirements with the VA and a Utah-licensed mortgage banker.

This article sits inside our VA loans coverage. For the full picture, start at the Utah VA loan specialist page, browse the VA Loan Resource Center, read about Tres Miller, or schedule a 15-minute consultation.

Related reading: eligibility and your COE, entitlement, VA appraisals, the funding fee, and the IRRRL streamline refinance.

Keep learning

Related consumer guides
Related calculators
  • Utah VA Loan Calculator
    Estimate a zero-down Utah VA loan payment, model the VA funding fee, and compare VA against FHA and conventional financing.
  • Utah Mortgage Calculator
    Estimate a Utah mortgage payment including principal, interest, taxes, and insurance.
Related knowledge assets
  • VA Loan Eligibility in Cedar Hills, Utah: Who Qualifies and What Documents Matter
    Who is eligible for a VA loan in Cedar Hills, Utah and exactly which documents a veteran should prepare before applying — the Certificate of Eligibility, DD-214 or Statement of Service, NGB-22 and point statements, disability award letters — plus how entitlement, the funding fee, occupancy, and the VA appraisal behave in northern Utah County.
  • VA Loan Entitlement in Cedar Hills, Utah: How First-Time and Repeat Use Works
    How VA entitlement works for a Cedar Hills, Utah buyer — what full entitlement means for a first-time user, how remaining entitlement is calculated when a prior VA loan is kept, when restoration is required, and how the funding fee, occupancy rules, and the Utah County loan limit shape the down payment.
  • The Complete Utah VA Loan Guide
    The VA home loan is the strongest financing benefit available to eligible Utah veterans, service members, and qualifying surviving spouses: no required down payment within entitlement, no monthly mortgage insurance, and a reusable lifetime benefit. This guide covers how the guaranty works, who qualifies, what a Utah VA purchase actually costs, funding-fee exemptions, appraisal and property requirements, entitlement reuse and assumptions, and the Utah-specific details that decide real transactions.
Tres Miller, Mortgage Banker, NMLS #217768

Written by

Tres Miller

Mortgage Banker · NMLS #217768 · U.S. Army veteran

Tres Miller is a Utah mortgage banker specializing in reverse mortgages and VA loans, with broader experience across Utah residential mortgage financing. A U.S. Army veteran, he has spent more than three decades helping Utah homeowners buy, finance, and protect their homes.

Specializing in reverse mortgages and VA loans, with broader work across Utah residential mortgage financing. Lending in Utah since 1995. Serving Utah County, Salt Lake County, Davis County, and all 29 Utah counties.

About TresProfessional historySchedule a consultation435-229-9797

Originally published September 12, 2026

Educational only. This asset does not constitute legal, tax, or financial advice. Programs, guidelines, and limits change frequently — verify current terms with a licensed Utah mortgage banker. Tres Miller serves homebuyers and homeowners throughout Utah — all 29 counties. Alpine, Highland, Cedar Hills, Mapleton, and Orem are a focus of our published content, not a limit on where mortgage services are provided. Tres Miller, Mortgage Banker, NMLS #217768 · JMJ Financial Group, Company NMLS #1866296 · Equal Housing Lender.

Ready to take the next step?

Talk to Tres — straight answers, real options, no pressure.