Utah Homeownership Authority
Tres“The Magic Mortgage Lender”Powered by JMJ Financial Group
VA Loans · Knowledge Center · UHA-0055

VA Loan Entitlement in Mapleton, Utah: How First-Time and Repeat Use Works

Remaining entitlement can still support a Mapleton purchase — once the guaranty gap is calculated before the offer.

By Tres MillerSeptember 17, 20269 min read
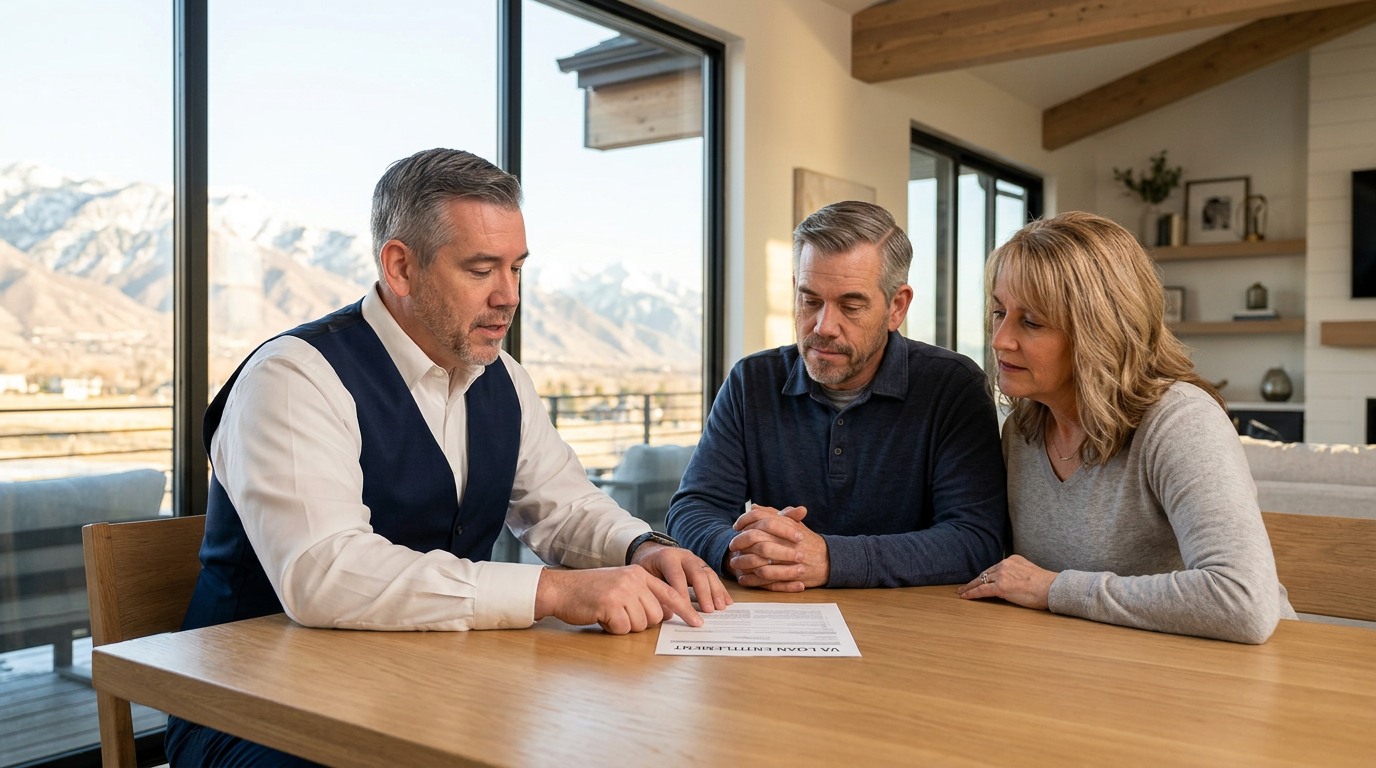
Tres “The Magic Mortgage Lender” Miller in his navy vest and white shirt reviewing a VA entitlement worksheet with veteran homebuyers in a Mapleton, Utah kitchen.
Tres “The Magic Mortgage Lender” Miller explains first-time and repeat VA entitlement to Mapleton, Utah homebuyers.

Executive summary

How VA entitlement works for a Mapleton, Utah buyer, including full entitlement, repeat use while keeping a prior home, restoration, the Utah County loan limit, funding-fee tiers, occupancy, and possible down-payment needs.

  • Entitlement is the VA's guaranty to the lender, not cash paid to the buyer.
  • Full entitlement removes the VA-imposed loan limit on a Mapleton purchase.
  • Remaining entitlement and the county loan limit determine any guaranty gap.
  • A buyer can sometimes keep a prior VA-financed home and use the benefit again.
  • Restoration must appear on an updated Certificate of Eligibility.
  • Every VA purchase requires primary-residence occupancy.

The direct answer

VA entitlement is the amount the U.S. Department of Veterans Affairs guarantees to a lender on your behalf. A first-time user in Mapleton, Utah with full entitlement generally has no VA-imposed loan limit and can finance a qualifying primary residence with no down payment. A repeat user has whatever entitlement remains after any active VA loan, and that remaining amount — measured against the Utah County loan limit — determines whether a down payment is required.

Entitlement is documented on your Certificate of Eligibility (COE), not estimated from memory. Pull a current COE before you write an offer in Mapleton so first-time or repeat status, restoration, and any remaining-entitlement gap are known while you can still act on them.

Executive summary

  • Entitlement is the VA's guaranty to the lender — not a cash benefit paid to you.
  • Full entitlement removes the VA-imposed loan limit; qualification and the appraisal still apply.
  • Partial (remaining) entitlement can still buy a home, often with a down payment.
  • The benefit is reusable; it is not a one-time program.
  • Restoration after paying off a prior VA loan must be requested and shown on an updated COE.
  • Two VA loans at once are possible with enough remaining entitlement and a valid occupancy reason.
  • The funding fee is typically higher on subsequent use unless you are exempt.

First-time use: what full entitlement means

Full entitlement generally applies when you have never used the VA home loan benefit, or when every prior VA loan has been paid in full and entitlement has been restored. With full entitlement there is no VA-imposed cap on the loan amount in Mapleton or anywhere else in Utah. The practical ceiling comes from three other places:

  • Lender qualification — income, credit, debt-to-income, and residual income standards.
  • The VA appraisal — value supported by comparable sales plus Minimum Property Requirements.
  • Your own payment comfort — taxes, insurance, and any association dues included.

If you are still confirming whether you qualify at all, start with the Mapleton VA eligibility and documents guide before working through entitlement.

Repeat use: remaining entitlement and restoration

Mapleton repeat buyers often arrive with equity in a prior home but an active VA loan they plan to keep. That can work when enough entitlement remains, yet the guaranty gap may still require a down payment even when income and credit easily support the new payment.

SituationEntitlement statusTypical effect in Mapleton
Never used the benefitFullNo VA-imposed limit; zero down is generally possible
Prior VA loan paid off and home soldRestorable to fullRequest restoration; confirm it on an updated COE
Prior VA loan still outstandingPartialGuaranty gap may require a down payment
Loan assumed by another veteranSubstitutedEntitlement can be released when the buyer substitutes theirs
Prior VA loan ended in a claimReducedRestoration may require repaying the VA's loss

A one-time restoration is also available in limited circumstances where a prior VA loan was paid in full but the home was kept. Because the rules are specific and change over time, confirm your case with the VA and your lender rather than with a forum post.

What is specific to Mapleton

Mapleton combines established neighborhoods, larger lots, and newer construction near the foothills. Purchase prices and property features vary widely, so a repeat VA buyer needs the entitlement calculation completed against the actual target price rather than relying on a rough countywide estimate.

  • Price points raise the stakes. In southern Utah County, the difference between full and partial entitlement often shows up as real cash to close.
  • Timelines are short. A manual COE or restoration request can outlast a Utah County contract if it starts after you are under contract.
  • Offer strength still matters. A fully underwritten pre-approval with a current COE reads very differently to a seller than a pre-qualification.

Nearby VA entitlement guides: Orem, Cedar Hills. Also see the VA entitlement explainer, the VA Loan Resource Center, and Tres Miller's Utah VA guidance.

Funding fee, occupancy, and second loans

The funding fee generally increases on subsequent use of the benefit when no down payment is made, and a larger down payment generally reduces it. Veterans receiving VA compensation for a service-connected disability and certain surviving spouses are exempt.

Occupancy applies to every VA purchase. The home you are buying in Mapleton must be your primary residence, generally occupied within a reasonable period after closing. Keeping a prior home as a rental is allowed; buying purely as an investment is not.

Compare a Mapleton payment with and without a financed funding fee in the VA Loan Calculator, and review how the funding fee is set before deciding whether to finance it.

How Tres would evaluate this

A veteran keeps a VA-financed starter home and plans to move to a larger Mapleton property. Tres pulls the current COE, calculates the remaining guaranty against the target price, and compares the required down payment with the proceeds and reserves available. The family sees the full cash picture before committing to the move.

This is an illustrative decision framework, not a description of a specific client or completed transaction.

What to verify before you decide

  • The remaining entitlement figure shown on your current COE.
  • Whether restoration from a prior VA loan has actually been processed.
  • The current Utah County loan limit used in the guaranty calculation.
  • Any down payment required to close the guaranty gap at your target price.
  • Your funding-fee tier, or your exemption if you are rated.
  • The occupancy plan for both the new home and any home you keep.
  • Total payment and cash to close compared with other suitable financing.

Verify current entitlement, loan-limit, funding-fee, and occupancy rules with the U.S. Department of Veterans Affairs and a Utah-licensed mortgage banker.
Myths vs. Facts

Myth

The VA benefit can only be used once.

Fact

It is reusable, and entitlement is generally restorable after a prior VA loan is paid in full.

Myth

You must sell your current home before reusing the benefit.

Fact

Not always. Sufficient remaining entitlement and a valid occupancy reason can support a second VA loan.

Myth

Partial entitlement means you cannot buy in Mapleton.

Fact

A down payment can cover the guaranty gap when partial entitlement is not enough for zero down.

Myth

Restoration happens automatically.

Fact

It must be requested and confirmed on an updated COE.

Myth

The funding fee is always the same.

Fact

It varies by prior use and down payment, and exempt veterans pay none.

Common mistakes to avoid
  • ·Estimating entitlement instead of using a current COE.
  • ·Assuming a prior payoff restored entitlement automatically.
  • ·Writing a zero-down offer before calculating the guaranty gap.
  • ·Missing a funding-fee exemption.
  • ·Ignoring both housing payments when keeping a prior home.
  • ·Treating the Mapleton property as an investment instead of a primary residence.
Today's action

Request a current Certificate of Eligibility, calculate remaining entitlement at your Mapleton target price, and compare the payment and cash required in the VA Loan Calculator.

Utah VA Buyer Cash-to-Close Worksheet (PDF)
Download PDF

Frequently Asked Questions

Ask the Authority
  • ?How much VA entitlement do I have left?
  • ?Can I keep my current home and buy in Mapleton?
  • ?What down payment would partial entitlement require?
  • ?Has my prior entitlement been restored?
  • ?Am I exempt from the VA funding fee?

This asset is educational only and is not legal, tax, or personalized financial advice, and it is not a loan approval or commitment to lend. VA eligibility, entitlement, loan-limit, funding-fee, and occupancy rules change; confirm current requirements with the VA and a Utah-licensed mortgage banker.

This article sits inside our VA loans coverage. For the full picture, start at the Utah VA loan specialist page, browse the VA Loan Resource Center, read about Tres Miller, or schedule a 15-minute consultation.

Related reading: eligibility and your COE, entitlement, VA appraisals, the funding fee, and the IRRRL streamline refinance.

Keep learning

Related consumer guides
Related calculators
  • Utah VA Loan Calculator
    Estimate a zero-down Utah VA loan payment, model the VA funding fee, and compare VA against FHA and conventional financing.
  • Utah Mortgage Calculator
    Estimate a Utah mortgage payment including principal, interest, taxes, and insurance.
Related knowledge assets
  • VA Loan Eligibility in Mapleton, Utah: Who Qualifies and What Documents Matter
    Who is eligible for a VA loan in Mapleton, Utah and exactly which documents a veteran should prepare before applying — the Certificate of Eligibility, DD-214 or Statement of Service, NGB-22 and point statements, disability award letters — plus how entitlement, the funding fee, occupancy, and the VA appraisal behave in southern Utah County.
  • VA Loan Entitlement in Cedar Hills, Utah: How First-Time and Repeat Use Works
    How VA entitlement works for a Cedar Hills, Utah buyer — what full entitlement means for a first-time user, how remaining entitlement is calculated when a prior VA loan is kept, when restoration is required, and how the funding fee, occupancy rules, and the Utah County loan limit shape the down payment.
  • The Complete Utah VA Loan Guide
    The VA home loan is the strongest financing benefit available to eligible Utah veterans, service members, and qualifying surviving spouses: no required down payment within entitlement, no monthly mortgage insurance, and a reusable lifetime benefit. This guide covers how the guaranty works, who qualifies, what a Utah VA purchase actually costs, funding-fee exemptions, appraisal and property requirements, entitlement reuse and assumptions, and the Utah-specific details that decide real transactions.
Tres Miller, Mortgage Banker, NMLS #217768

Written by

Tres Miller

Mortgage Banker · NMLS #217768 · U.S. Army veteran

Tres Miller is a Utah mortgage banker specializing in reverse mortgages and VA loans, with broader experience across Utah residential mortgage financing. A U.S. Army veteran, he has spent more than three decades helping Utah homeowners buy, finance, and protect their homes.

Specializing in reverse mortgages and VA loans, with broader work across Utah residential mortgage financing. Lending in Utah since 1995. Serving Utah County, Salt Lake County, Davis County, and all 29 Utah counties.

About TresProfessional historySchedule a consultation435-229-9797

Originally published September 17, 2026

Educational only. This asset does not constitute legal, tax, or financial advice. Programs, guidelines, and limits change frequently — verify current terms with a licensed Utah mortgage banker. Tres Miller serves homebuyers and homeowners throughout Utah — all 29 counties. Alpine, Highland, Cedar Hills, Mapleton, and Orem are a focus of our published content, not a limit on where mortgage services are provided. Tres Miller, Mortgage Banker, NMLS #217768 · JMJ Financial Group, Company NMLS #1866296 · Equal Housing Lender.

Ready to take the next step?

Talk to Tres — straight answers, real options, no pressure.